
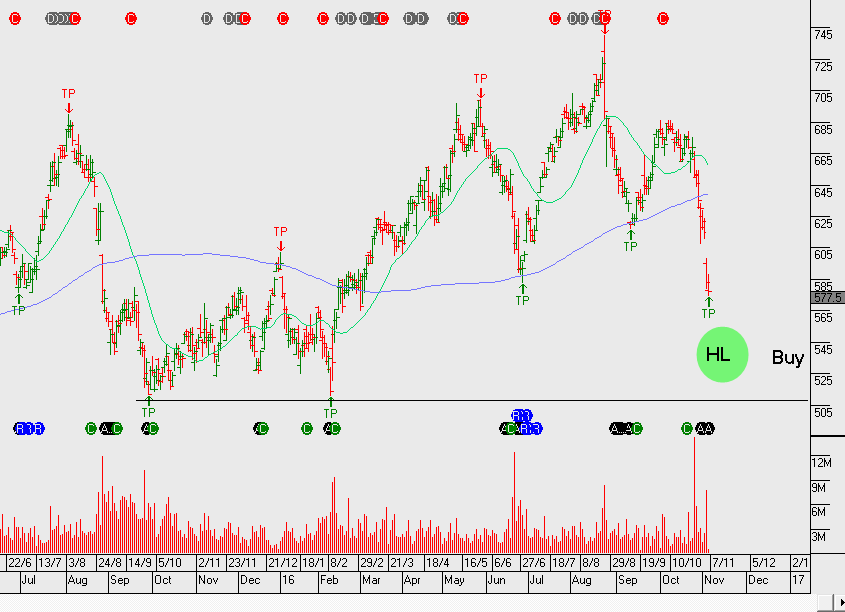
The Boral AGM provided an update on 1QFY17 earnings due to weather impacts and a slowdown in WA, FY17 earnings are now tracking below market expectations.
We continue to like BLD and JHX as exposure to improving infrastructure markets in Australia and ongoing positive trends within US housing. The sell-off in BLD is probably overdone and it’s worth adding this to your watch list. $5.50 as a potential buy level on any further weakness should be monitored as an entry point.
Y18 revenue growth 5% to $4.2b, EBIT growth into FY18 of 8% or $450m, EPS of $0.40 and DPS of $0.25 places the stock on an FY18 yield of 4.5%
