
RIO is likely to free up additional capital through the proceeds from the complete exit of coal and high cost aluminium smelting.
We estimate that this could raise more than $7.5 billion, potentially more than doubling shareholder cash returns in FY19
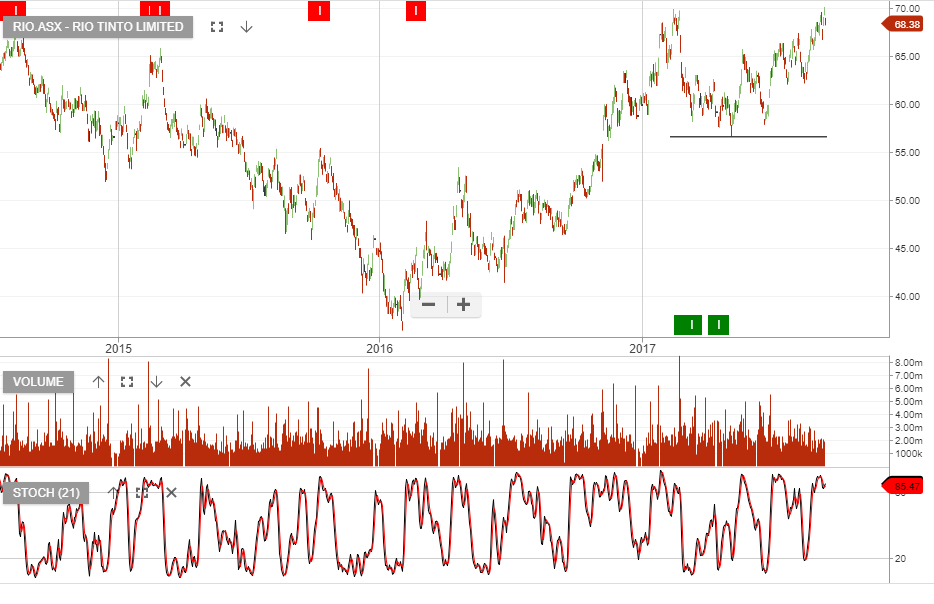
Recent sentiment around iron-ore and aluminium have helped drive RIO’s share price. We consider RIO near the top end of the valuation range.
However the share price should remain well supported, and when complimented with a covered call, we’re delivering 12% annualised cash flow.
FY 18 EBIT forecast of $9.8 billion, EPS $4.50 and DPS $2.45, places the stock on a forward yield of 4%.
Rio Tinto