
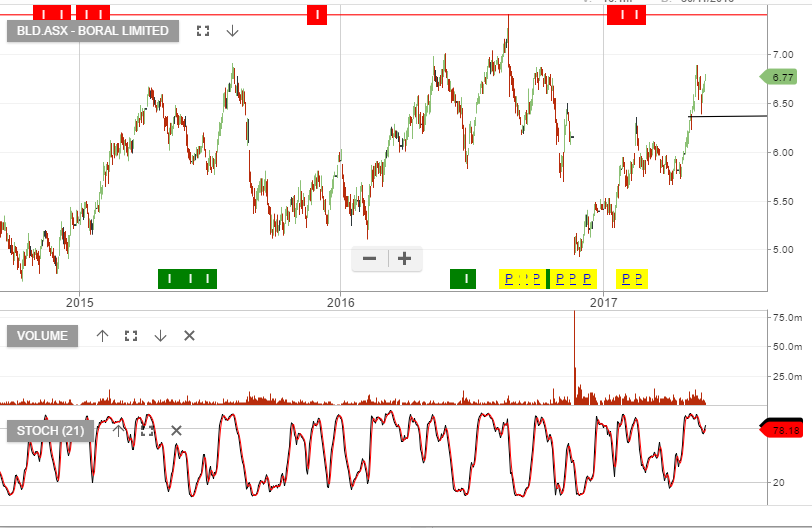
The market remains optimistic about future earnings growth for Boral. The recent Headwater acquisition in the US provides Boral with added exposure to the US housing market. Domestically, Boral is well placed to benefit from the an increase in large scale infrastructure projects.
We feel some caution is warranted though, given the weaker trends emerging is both US and domestic housing construction data. The stock trades on 19x forward earnings and less than a 4% yield.
FY18 revenue is likely to be $5.8b, EBITDA $1.15b, Net Profit $490m and DPS of $0.29.
