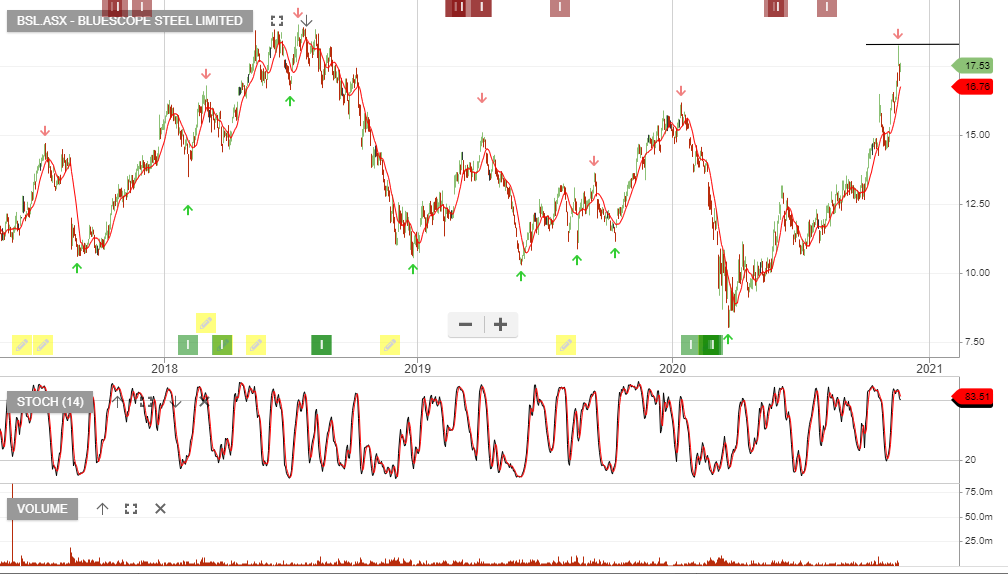
Housing demand, across renovation and new construction is driving strong demand for painted and coated steel products.
BSL upgraded 1H21 EBIT guidance by 25% to $475m.
We expect earnings to remain strong with top line revenue growth of 5 – 8% and underlying profit to increase by a similar number. This supports a 1% forward dividend yield.
We consider BSL full value and suggest investors wait for a pullback and the next Algo Engine buy signal.