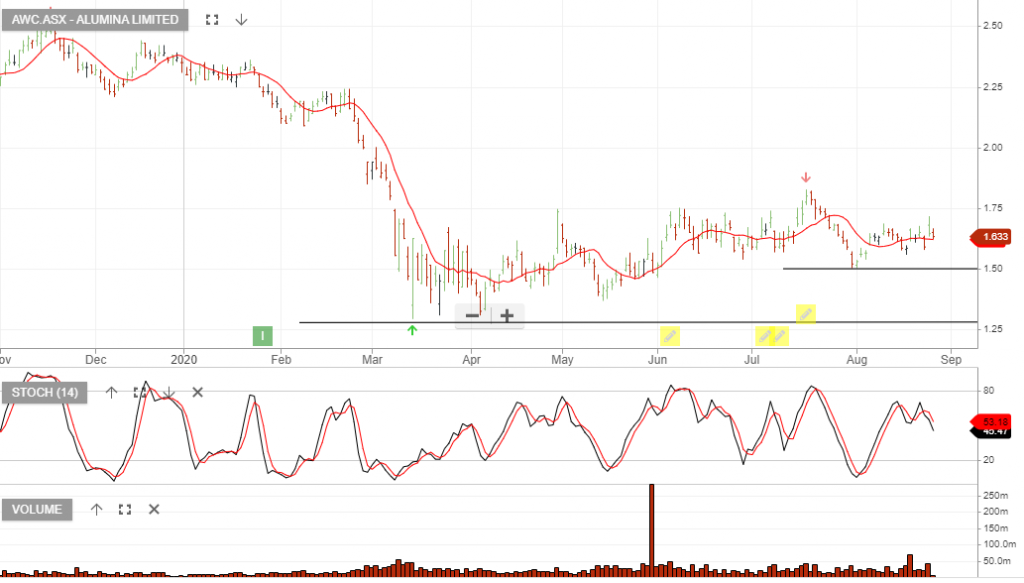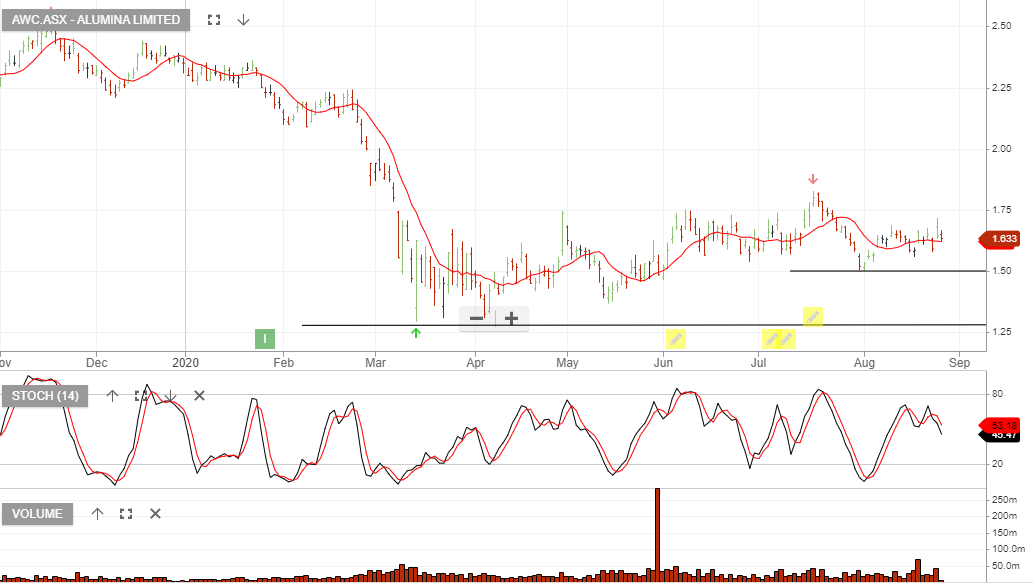
Alumina is under Algo Engine buy conditions and is a current holding in our ASX 100 model.
We recently focused on adding AWC to portfolios at $1.50 per share and have become somewhat concerned regarding the implications of the ATO back tax issues the company now faces.
Taking a closer look at 1H20 earnings, underlying NPAT was above consensus at $US88.
China’s recovery continues to support pricing momentum and AWC has lagged the alumina price rebound. Over the next 1 – 2 years, China is expected to have a metallurgical alumina deficit.
With the above in mind, we expect the $1.50 support level to hold but suggest a stop-loss on a break below.
The stock remains under review although we acknowledge the bullish outlook among institutional analysts.
FY21 dividend yield is 2.2%.