
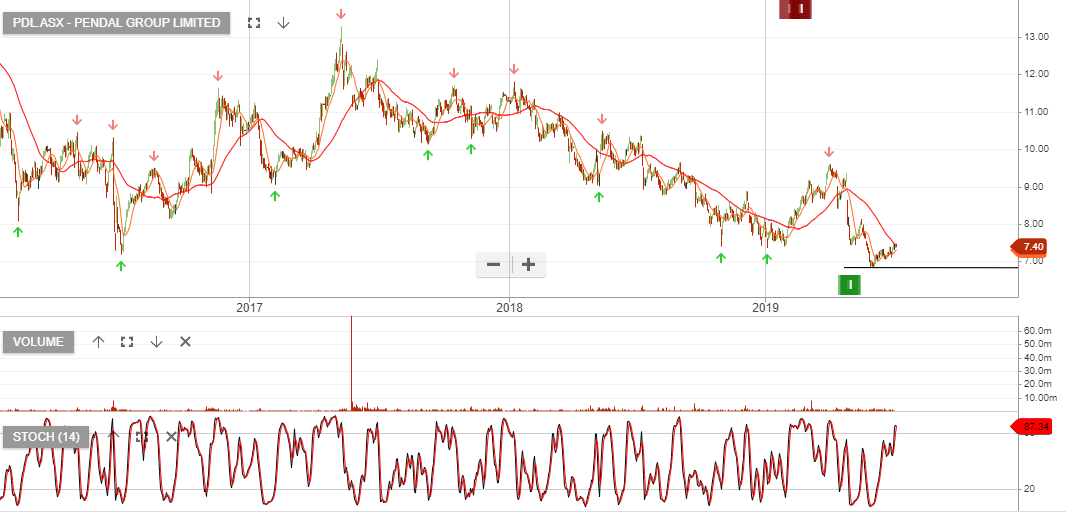
Pendal Group is under Algo Engine buy conditions and is a recent addition to our ASX 100 model portfolio.
The current 13x forward earnings multiple offers a discounted entry level.
FY20 revenue is set to increase by 10% to $550mn, EBIT +10% to $230mn, DPS increases by 10% to $0.50, placing the stock on an attractive 6.6% yield.
We are not applying a high conviction call to PDL, due to structural challenges facing the business, however, we highlight that the current share price reflects a more bearish scenario, than what is likely to playout over the next 1 – 2 years.
